Q: You really should consider posting about how you two budget and save for your purchases and DIY. I’m constantly amazed at how you seem to never charge anything and how you consistently mention saving up for things. Now just tell us how you do it!! What about making the decision to replace something that still works? Is that a hard call for you guys? I never know when to live with something, replace it with something semi-cheap for the interim or save up for the big thing I actually want and go right to buying that instead of putting money towards a placeholder while I save. I’d love to know more about how you know when to save and when to splurge and how you live such a debt free life full of projects and home makeovers! -Barbara
A: The short version: we learned to save from our parents, we prioritize what matters most, and we avoid debt whenever possible. Both John and I grew up with frugal role models, and that upbringing shaped how we handle money. We try to pay balances in full, resist impulse purchases when we don’t have the cash, and focus on spending intentionally.
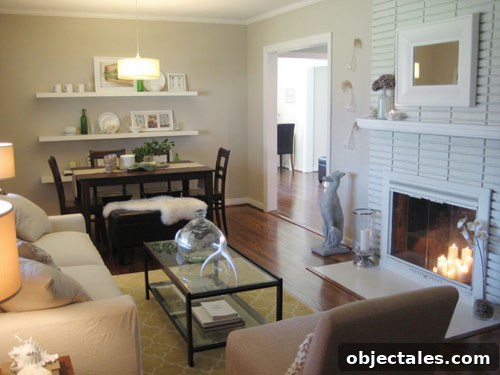
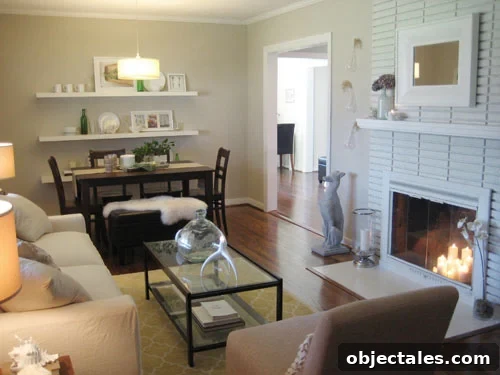
Our furnishing approach tends to be practical and value-driven. A lot of our home is filled with affordable finds that function well and still look good: a dining table purchased for around $150, thrift store chairs, a consignment coffee table. We don’t buy junk, but we also don’t assume the most expensive option is best. If a solid, well-reviewed table at a lower price point fits our needs, we’ll choose it and keep our savings intact. That mindset helps us fund bigger purchases without going into debt.
When something really matters to us, we save up for it. We’ve saved for an organic mattress and for a reliable car, paying for them in cash on the day we picked them up. The process is straightforward: decide the target, set aside money consistently, and wait until the funds are available. Meanwhile we hunt for sales, use coupons, compare reviews, and shop secondhand when it makes sense. This lets us enjoy occasional splurges without derailing our financial stability.
Location plays a role too. Moving from Manhattan to Richmond dramatically lowered our cost of living, which made saving and renovating more realistic. Our mortgage is much less than our old NYC rent, and buying a fixer-upper rather than a fully renovated house meant we could spread renovation costs over time without taking on excessive debt.
We also embrace frugal daily habits: sharing one car, borrowing books from the library, packing lunches, and doing DIY projects whenever feasible. We cut many recurring costs that add up—dining out is rare, clothing purchases are minimal, and we make our own cleaning products and even give each other haircuts. Those small sacrifices free up money for priorities like home improvements and paying off purchases immediately.
When deciding whether to replace something that still works, our rule of thumb is simple: if it truly bothers us and we can afford to replace it without using credit, we save up and buy the upgrade. We avoid buying temporary, low-quality “placeholders” that we’ll just resent later. Instead we either live with the item a bit longer, refresh it creatively with paint or minor fixes, or save for the long-term solution. We also sell the working item we replace—often on local marketplaces—so it doesn’t go to waste and its resale value offsets part of the replacement cost.
Communication is key for larger projects. Before starting a major remodel we discuss budgets in detail and save the full anticipated amount when possible. For example, we estimated a bathroom remodel might cost $3–5K, saved toward the high end, and ended up completing it for far less by doing the labor ourselves and sourcing deals. Having the cash on hand removed stress and made the project enjoyable instead of anxiety-inducing.
We tend to overestimate costs rather than come up short. Keeping renovation funds in a savings account before beginning a project is a deliberate choice that keeps us flexible and calm. It’s easier to make smart decisions on paint colors or fixtures when you’re not constantly worried about how to pay the next bill.
Deal-hunting pays off: thrift store chairs, Craigslist dressers that get refinished, clearance finds—these efforts let us create rooms we love without large outlays. Refinishing secondhand furniture often yields higher-quality results than buying cheap new pieces, and it’s kinder to the budget and the planet.
On average we probably spend five to ten percent of our income on home improvements, though that number fluctuates. Because home projects are a priority—and because my work as a home blogger requires new content—we choose to be strict elsewhere, like maintaining a one-car household and avoiding financing for everyday purchases.
For readers trying to save: look honestly at recurring expenses and trim what you can. Skip one restaurant meal a week, pause clothing purchases for a month, or try living with one vehicle. Small changes add up quickly and can fund meaningful goals when combined with consistent saving. Resist impulse buys and aim to purchase the items and projects that truly bring long-term satisfaction.
In short: prioritize, save, avoid debt, and hunt for value. Make temporary fixes when they make sense, but don’t waste money on placeholders you’ll regret. Save deliberately for the things that matter, and the upgrades will be far more satisfying when they arrive. We’d love to hear how you save and what strategies work in your household—share your tips and systems.
Pssst—If you want more detailed tips about saving and frugal living, check out the previous posts in our Save It series and other money-saving articles on the site for practical examples and step-by-step projects.