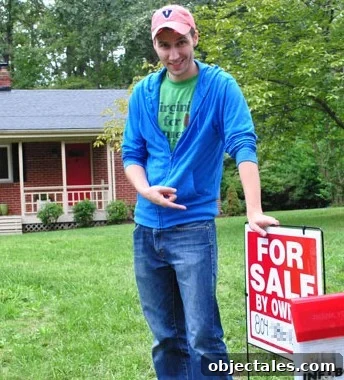
Are we kidding? In this market? Absolutely not. We sold our house for about $5,000 more than we bought it for back in 2006 — during the height of the bubble — and yes, we know we spent far more than that on improvements. We estimate roughly $35,000 went into upgraded bathrooms, a new kitchen, new flooring and windows, a new roof, a paved driveway and patio, and finishing touches like crown molding and wider doorways. It’s a humbling math problem, but it hasn’t left us regretful.
Why are we sleeping soundly and actually excited about both selling our old house and buying a new one? Because the timing felt right, and everything fell into place. Maybe it sounds optimistic — but here’s how we’re thinking about it.
- Our new monthly mortgage payment is $200 less than what we were paying for the smaller old house. Low interest rates and a favorable purchase price made a larger home in a better neighborhood more affordable each month. More space, better location, and lower payments — a rare win in today’s market.
- Comparables in our old neighborhood that didn’t receive updates are selling for $30K, $40K, even $50K less than our sale price. That makes the improvements feel worthwhile: not only did we enjoy the upgrades while living there, but they helped preserve and even increase our home’s value despite an overall weaker market.
- We received an offer within days of listing on MLS. In a market where many homes linger unsold for months, that quick sale is something we’re genuinely grateful for.
For context: we’re not professional flippers — we’re homeowners who cared about creating a comfortable, functional home while we lived there. Every renovation was intended for our daily life, not purely for profit. The fact that those updates also protected our home’s value through a downturn feels like a lucky bonus. We’re especially glad about the driveway and cobblestone patio: diverting the venue budget for our backyard wedding to those improvements let us celebrate outdoors and left us with durable, useful features that outlasted the event. The kitchen renovation even helped launch a blog that grew into a business, enabling us to work from home with our kids nearby.
As buyers in this same market, we also see clear benefits. We purchased a larger house in a nicer neighborhood at a significant discount — roughly $40K less than its valuation five years ago. With interest rates currently low, we stand to save thousands in interest over the life of the loan. We used the equity from our old home to help fund this purchase, and that combination of equity and low rates is how our new mortgage ended up cheaper month-to-month.
We weighed the possibility of waiting for the market to improve, which might have yielded a higher sale price for our old place. But waiting has risks: houses like our new one could easily have climbed back out of our budget if prices recovered. Buying now gave us the home that fits our family and our creative work, and that daily satisfaction outweighs speculative gains down the road.
Let’s return to the $35K we invested and the $5K price increase we realized at sale. On paper it can look like a loss: we paid more than we recouped. But context matters. Comparable properties without updates sold for far less than ours. A notably larger ranch a few houses down sold this summer for about $50K less than our price. That comparison makes our renovations feel wise: they helped our house hold value and even edge up slightly since the bubble. It’s a small comfort to view the outcome as preventing a steeper drop rather than as a straightforward loss.
Our lender offered another perspective that rings true: not every improvement returns dollar-for-dollar at sale, but many accelerate the selling process. Buyers may not pay a huge premium for granite counters, for example, but a renovated kitchen can attract offers far faster than an unrenovated one. We were under contract two days after listing; a similar, larger house down the road has been listed for months with no offers, even though it’s priced lower.
Would we prefer a stronger market? Of course. But we have no regrets. Some might call our view optimistic, and selling now isn’t the right move for every homeowner. For us, though, the combination of a home that fits our family, a stronger neighborhood, lower monthly payments, and the ability to continue our work from home made this the right decision. We’re excited to spend the holidays in our new house, and besides — there are boxes to unpack.