Q: You really should consider posting about how you two budget and save for your purchases and DIY. I’m constantly amazed at how you seem to never charge anything and how you consistently mention saving up for things. Now just tell us how you do it!! What about making the decision to replace something that still works? Is that a hard call for you guys? I never know when to live with something, replace it with something semi-cheap for the interim or save up for the big thing I actually want and go right to buying that instead of putting money towards a placeholder while I save. I’d love to know more about how you know when to save and when to splurge and how you live such a debt free life full of projects and home makeovers! -Barbara
A: We learned our money habits from frugal dads, so saving up, paying off credit cards in full, and avoiding purchases we can’t afford immediately have been a big part of our approach. It takes discipline and often means walking away from tempting deals, but if we can’t pay cash for something, it rarely feels like a true bargain to us.
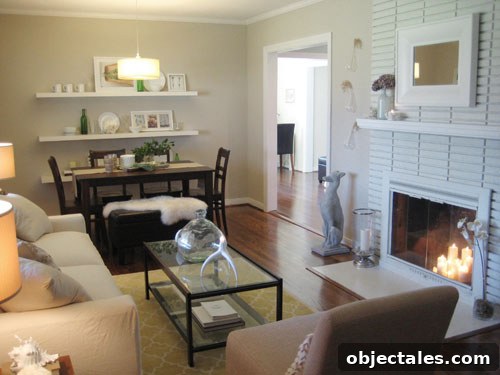
Many of our everyday items are simple and affordable: our dining table came from a big-box store for around $150, a thrift-store chair lives in our den, and a consignment coffee table sits in the living room. We don’t buy cheap junk for the sake of saving, but when a well-reviewed, sturdy option is available for a fraction of the price of an upscale competitor, we’ll usually choose the thrifty pick and keep the savings in the bank. That balance lets us afford occasional splurges on things that matter a lot to us, like an organic mattress or a reliable car, both of which we saved up for and bought outright.
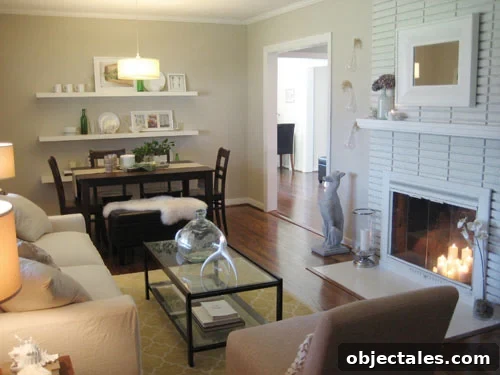
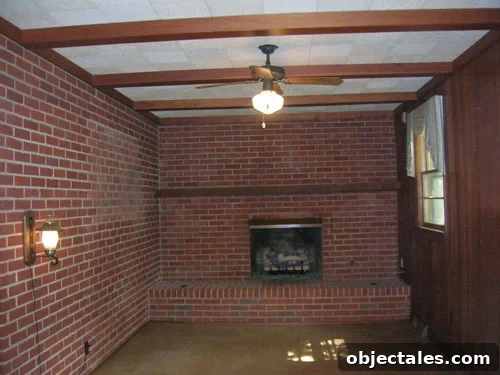
Location helps, too. Living in a lower-cost city after years in an expensive metro area made it much easier to save. Our mortgage is far lower than what we used to pay in rent, and we bought a fixer-upper that cost significantly less because it needed work. That allowed us to invest in renovations gradually rather than paying a premium for a move-in-ready home.
Beyond shopping smart, we cut expenses in everyday life: sharing one car, borrowing books from the library, making bagged lunches, doing DIY projects (from tiling to haircuts), and making household cleaners at home. Those consistent savings add up and let us funnel funds toward renovation projects and long-term purchases without relying on credit.
When deciding whether to replace something that still works, we think about how much it bothers us and whether the replacement will be worth the cost. If the item makes us cringe or costs too much in energy or frustration—like an inefficient, yellowed refrigerator—we save up until we can buy the replacement in cash. We also resell the old working item locally so it doesn’t end up in a landfill and to recoup some money to put toward the new purchase.
We avoid buying temporary “placeholder” items most of the time. Buying something cheap to tide us over usually ends in regret because it becomes wasteful spending when you still want the higher-quality, permanent piece. That said, a temporary fix can make sense for some people—if a $50 interim chandelier relieves stress while you save for the $250 version you truly want, that’s a reasonable choice. The key is to weigh what will actually make you happier and what you can realistically afford.
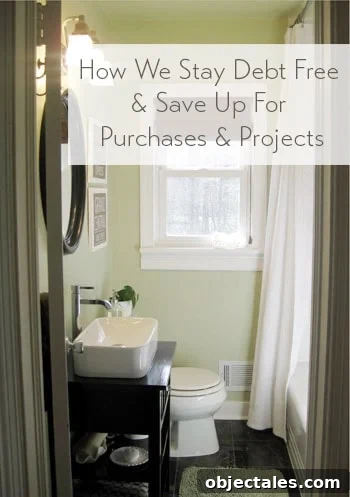
For larger projects, we plan and discuss costs thoroughly before we start. For instance, we estimated a bathroom remodel might cost $3,000–$5,000 and saved toward the higher end. We were pleasantly surprised to complete it for $1,800 by doing all the labor ourselves and hunting down great deals, which left us ready to move on to the next project with money still in savings. Having the funds in the bank before you begin a renovation removes a lot of stress and makes the work more enjoyable.
Deal-hunting is part of our routine: thrift stores, Craigslist, clearance racks, and DIY refinishing can stretch your budget much further than buying new. For our nursery, we found a $20 thrift chair and a $20 Craigslist dresser, then refinished the dresser to look like new. Taking the time to look for quality secondhand furniture that you can restore often yields much better long-term value than off-the-shelf cheap pieces.
On average, we spend roughly five to ten percent of our income on home improvements, though that fluctuates with projects and is a personal choice for each household. Because home projects are a priority for us, we keep other expenses low—one car, paid off; modest dining out; minimal clothing expenses; and DIY personal care—to free up cash for remodeling and furnishing.
If you want to save for a big item or renovation, start by identifying small habitual expenses you can cut—coffee runs, frequent dining out, or an extra vehicle. Even temporary challenges, like a clothing-buying hiatus for a month, can quickly add up. Consider selling items you no longer need to boost your savings, or downgrade a luxury purchase in one area to prioritize another.
Our core advice is simple: don’t spend beyond your means, save for what truly matters, and avoid impulse buys that chip away at your renovation or savings goals. Use inexpensive fixes and things you already have to tide you over, hunt for deals, and keep renovation funds saved in the bank before starting a project. That approach keeps projects fun and stress-free, and it’s helped us live a largely debt-free life centered around projects and home improvements.
We’d love to hear how you save and prioritize—what methods work for you? Any envelope-system fans out there? Share your tips and experiences.
Pssst—If you want more saving ideas, check our posts about living with less, simple money-saving swaps, and step-by-step project write-ups to see how we save and spend thoughtfully at home.