
How Much Profit Did We Make Selling Our First House?
Why We Sold and Bought a Home in This Market: Lessons from Our Move
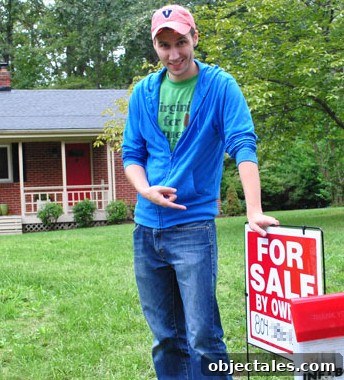
We know what you’re thinking: “Sell in this market?” It sounds risky, but for us the timing and circumstances made it the right call. We sold our old house for roughly $5,000 more than we paid for it in 2006—despite investing substantially in upgrades. We estimate spending about $35,000 on new bathrooms, a renovated kitchen, new flooring, replacement windows, a new roof, a paved driveway and patio, and finishing touches like crown molding and wider doorways. On paper it might look like a loss when you compare purchase price plus improvements to the sale price, but the reality is more complex.
We’re sleeping well and genuinely excited about both the sale and our new purchase. Why? Because we believe everything worked out the way it should. Here’s the thinking that led us to sell and buy now:
- Our monthly mortgage payment on the new house is about $200 less than what we were paying for our smaller, older house. That’s thanks to the current low interest rates and a very favorable deal on the new property. More house, in a better neighborhood, for less each month—hard to argue with that.
- Comparable, unimproved homes in our old neighborhood are selling for $30K, $40K, or even $50K less than what we achieved. Our renovations helped preserve—and even slightly increase—our property’s value, despite buying at the height of the market and selling when conditions were tougher.
- We received an offer within a few days of listing on the MLS, which is remarkable in a buyers’ market and something to be grateful for.
If you want the details, here’s more context: we’re not house flippers. We renovated our old home because we loved it and wanted it to function well for our family while we lived there. That meant the improvements delivered real value to our everyday life—plus benefits at resale. For example, funds we saved by hosting an inexpensive backyard wedding allowed us to invest in a paved driveway and cobblestone patio that outlived the event. Our kitchen renovation also turned into a project that catalyzed a blog and a business, enabling work-from-home flexibility that’s been invaluable for family life.
On the buying side, this has been a rare opportunity. We purchased a larger house in a nicer neighborhood at a substantial discount—over $40,000 less than its value five years ago—and at historically low interest rates. That combination reduces our long-term interest costs and helped us roll equity from our sale into a mortgage payment that’s lower than before. In short: we traded up without trading off financial stability.
We also weighed potential future gains. If the market rebounds someday, our new house has more upside than our old house would have had. Waiting to sell might have increased the sale price of our old home, but it also could have kept the kind of house we wanted out of reach—just like it was five years ago. Beyond finances, the new house fits our lifestyle: it offers room to grow, more DIY potential, and space that supports our business. Those day-to-day benefits matter a lot.
Let’s revisit the $35,000 in improvements versus the roughly $5,000 net gain in sale price compared to purchase. Although the numbers on paper might suggest a loss, the improvements did protect value and helped our home stand out. Nearby houses lacking updates have been selling for much less—one larger ranch just a few houses away sold this summer for $50,000 less than ours did. That underscores how meaningful targeted improvements can be in preserving resale value and accelerating a sale.
Our lender also pointed out a trend we’ve seen firsthand: homeowners aren’t always recouping improvement costs dollar-for-dollar, but they are often recouping them in the speed of sale. Buyers tend to make offers much faster on homes with higher-quality finishes. We were on the market for only two days before receiving an offer, while a similar, larger house down the street has lingered for months even though it’s listed for $30,000 less.
Do we wish the market were stronger? Of course. But we have no regrets. We recognize this approach won’t be right for everyone, and we’re not claiming it’s a universal playbook. For us, the combination of a faster sale, a better home in a stronger neighborhood, a lower monthly payment, and the lifestyle benefits of our renovations made selling now the right decision. And most importantly, we’re moving into the holidays excited to celebrate Clara’s first Christmas in our new home—which feels like the best measure of success. Now, if you’ll excuse us, we’ve still got boxes to unpack.







