In a tight economy, it’s hard to avoid talking about money — especially when you’re reflecting on a major home renovation during our blogiversary week. We wanted to revisit the most expensive project in Young House Love history and share how a few smart choices helped make the cost more manageable.
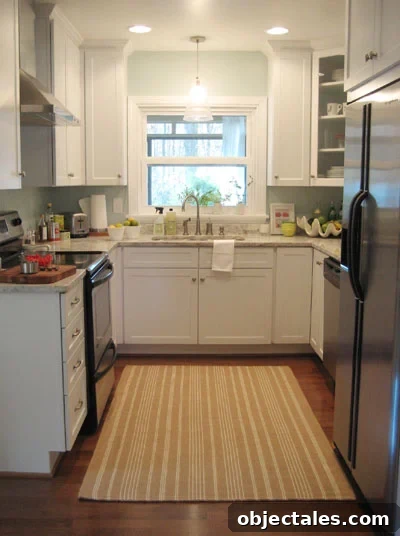
You may have seen photos of our kitchen remodel; if not, they’re widely available on the site. Earlier this year we published a detailed cost breakdown of that massive project, opening up our numbers so readers could see where every dollar went. The total came to $17,500, but by negotiating with contractors, timing purchases around sales, and buying discounted items, we reduced that amount by roughly $5,500. That kind of saving proves you can get savvy with money and still invest in higher-end finishes when it matters most.
Beyond negotiating and bargain hunting, one of the lesser-discussed strategies we used was leveraging a temporary, interest-free credit offer to our advantage. When the bill for cabinets, countertops, and installation came to around $14,000, we opened a retailer credit account during a “no interest or payments for six months” promotion. Although we had the cash available to pay immediately, we chose a short-term financial strategy that let us keep the money working for us for a while longer.
This approach requires discipline. Putting a large purchase on a promotional credit line while keeping the actual funds in a high-yield savings account can feel counterintuitive, especially for anyone who dislikes carrying debt. We considered the risks carefully and set a firm timeline: invest the cash safely, track any earned interest, and be ready to clear the credit balance before the promotional period ended to avoid fees or retroactive interest charges.
In our case the plan paid off. By keeping the $14,000 in a high-yield savings account for six months and then using that money to pay the credit balance before the promotion expired, we earned roughly $210 in interest. It’s not a life-changing amount, but it’s real money that offset part of the remodel costs and made a few finishing touches feel essentially free. For example, subtracting that earned interest from our out-of-pocket expenses made small luxury items — like a new faucet and a seeded glass pendant — feel less like splurges and more like affordable upgrades.
This strategy isn’t a one-size-fits-all solution. It works best when you already have the funds in place, can confidently meet the promotional deadline, and choose a safe, liquid place for those funds so they remain accessible when it’s time to pay. It also requires strict self-control: you must not tap the cash for other things, and you must be organized about repayment to avoid penalties. If you plan carefully and understand the terms of the credit offer, the risk can be low and the benefit — even modest — can add up across a large project.
Aside from financing tactics, simple habits helped reduce our overall bill: vetting contractors thoroughly, comparing multiple bids, timing purchases for sales events, and being willing to source certain items from discount outlets or clearance sections. Combining those everyday money-saving habits with smarter short-term financing allowed us to maintain the vision for our kitchen without blowing the budget.
We’re curious to hear what’s worked for you. Do you have creative ways you’ve reduced renovation costs, or smart financing tips that helped make a big project less painful? Share your stories — we love practical, real-world solutions that make home improvement projects more achievable and less stressful.